Engineering and finance formulas in PDF
Control, circuits and structures sit next to interest, annuities and option pricing: the formulas of reports and coursework, typeset natively.
Transfer functions, the Nyquist criterion, Ohm and Kirchhoff, beam deflection and Reynolds number, then compound interest, annuities, net present value and the Black-Scholes model. Toggle: math.
Markdown source
Markdown · 56 lines# Engineering and finance formulas
## Signals and control
A first-order low-pass filter, its cut-off frequency and the sampling theorem:
$ H(s) = \frac{1}{1 + sRC} \qquad f_c = \frac{1}{2\pi RC} \qquad f_s > 2 f_{\max} $
$ |H(j\omega)| = \frac{1}{\sqrt{1 + (\omega R C)^2}} \qquad \text{gain in dB} = 20 \log_{10} |H(j\omega)| \qquad y[n] = \sum_{k=0}^{M} b_k\, x[n-k] - \sum_{k=1}^{N} a_k\, y[n-k] $
The PID controller and the discrete Fourier transform:
$ u(t) = K_p\, e(t) + K_i \int_0^t e(\tau)\,\mathrm{d}\tau + K_d\, \frac{\mathrm{d}e(t)}{\mathrm{d}t} \qquad X_k = \sum_{n=0}^{N-1} x_n\, e^{-2\pi i k n / N} $
## Electrical
$ V = IR \qquad P = VI = I^2 R = \frac{V^2}{R} \qquad \sum_{k} I_k = 0 \qquad Z = R + j\left(\omega L - \frac{1}{\omega C}\right) \qquad \omega_0 = \frac{1}{\sqrt{LC}} $
## Mechanical and civil
Deflection of a simply supported beam under a central load, stress and strain, and the Reynolds number:
$ \delta_{\max} = \frac{F L^3}{48\, E I} \qquad \sigma = \frac{F}{A} = E\,\varepsilon \qquad I_{\text{rect}} = \frac{b h^3}{12} \qquad \mathrm{Re} = \frac{\rho v L}{\mu} $
$ Q = A v \qquad p_1 + \tfrac{1}{2}\rho v_1^2 + \rho g h_1 = p_2 + \tfrac{1}{2}\rho v_2^2 + \rho g h_2 \qquad \Delta p = f\, \frac{L}{D}\, \frac{\rho v^2}{2} $
## Interest and loans
Compound interest, continuous compounding, and the payment on an annuity loan of principal $P$ at periodic rate $r$ over $n$ periods:
$ A = P \left( 1 + \frac{r}{m} \right)^{mt} \qquad A = P e^{rt} \qquad \text{payment} = P\, \frac{r (1 + r)^n}{(1 + r)^n - 1} $
A loan of $P = 250{,}000$ at $0.35\,\%$ a month over $n = 300$ months costs $250{,}000 \times \dfrac{0.0035 \cdot 1.0035^{300}}{1.0035^{300} - 1} \approx 1{,}518$ a month.
## Investment appraisal
$ \mathrm{NPV} = \sum_{t=0}^{T} \frac{C_t}{(1 + r)^t} \qquad \mathrm{IRR}: \sum_{t=0}^{T} \frac{C_t}{(1 + \mathrm{IRR})^t} = 0 \qquad \mathrm{WACC} = \frac{E}{V} r_E + \frac{D}{V} r_D (1 - \tau) $
The capital asset pricing model and the Sharpe ratio:
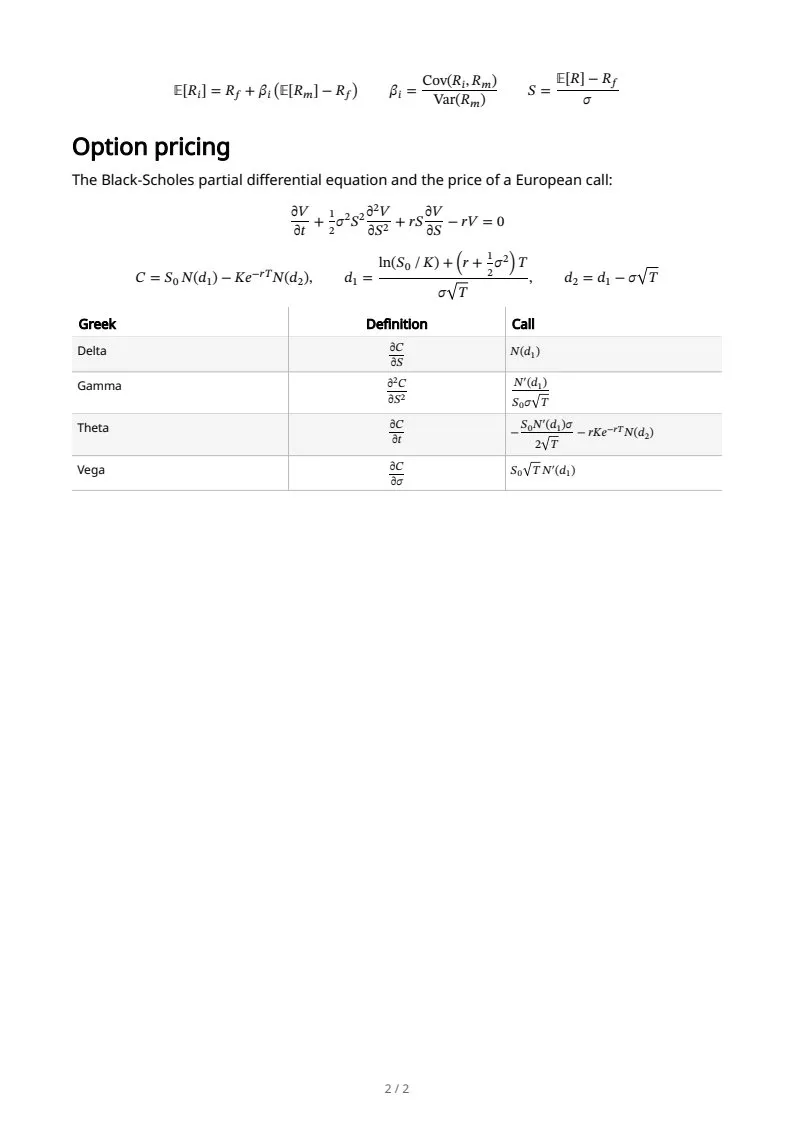
$ \mathbb{E}[R_i] = R_f + \beta_i \left( \mathbb{E}[R_m] - R_f \right) \qquad \beta_i = \frac{\operatorname{Cov}(R_i, R_m)}{\operatorname{Var}(R_m)} \qquad S = \frac{\mathbb{E}[R] - R_f}{\sigma} $
## Option pricing
The Black-Scholes partial differential equation and the price of a European call:
$ \frac{\partial V}{\partial t} + \tfrac{1}{2} \sigma^2 S^2 \frac{\partial^2 V}{\partial S^2} + r S \frac{\partial V}{\partial S} - rV = 0 $
$ C = S_0\, N(d_1) - K e^{-rT} N(d_2), \qquad d_1 = \frac{\ln(S_0 / K) + \left( r + \tfrac{1}{2}\sigma^2 \right) T}{\sigma \sqrt{T}}, \qquad d_2 = d_1 - \sigma \sqrt{T} $
| Greek | Definition | Call |
|:------|:----------:|:-----|
| Delta | $\dfrac{\partial C}{\partial S}$ | $N(d_1)$ |
| Gamma | $\dfrac{\partial^2 C}{\partial S^2}$ | $\dfrac{N'(d_1)}{S_0 \sigma \sqrt{T}}$ |
| Theta | $\dfrac{\partial C}{\partial t}$ | $-\dfrac{S_0 N'(d_1) \sigma}{2\sqrt{T}} - r K e^{-rT} N(d_2)$ |
| Vega | $\dfrac{\partial C}{\partial \sigma}$ | $S_0 \sqrt{T}\, N'(d_1)$ |
Rendered pages
PDF · 2 pages · 41 KB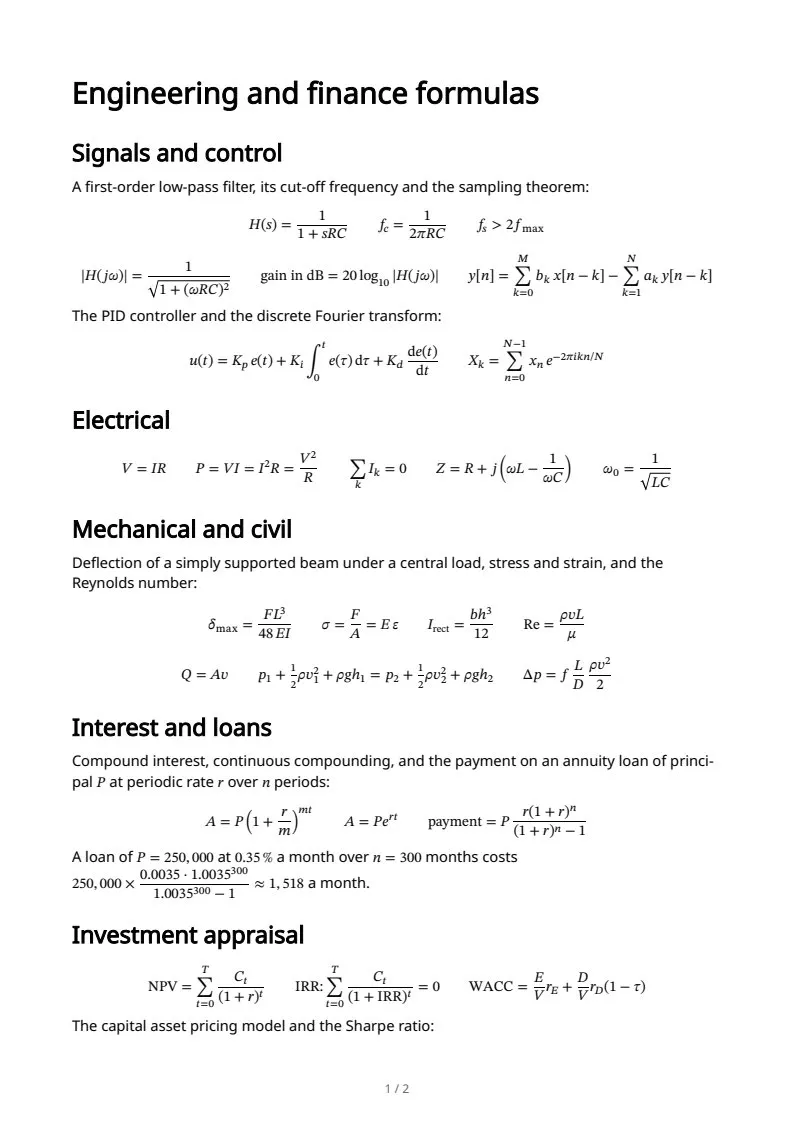
The sample documents describe invented organizations in several countries. All names and figures are illustrative.
LaTeX math in Markdown to PDF: every sampleIn the Markdown reference